The Invisible Cost
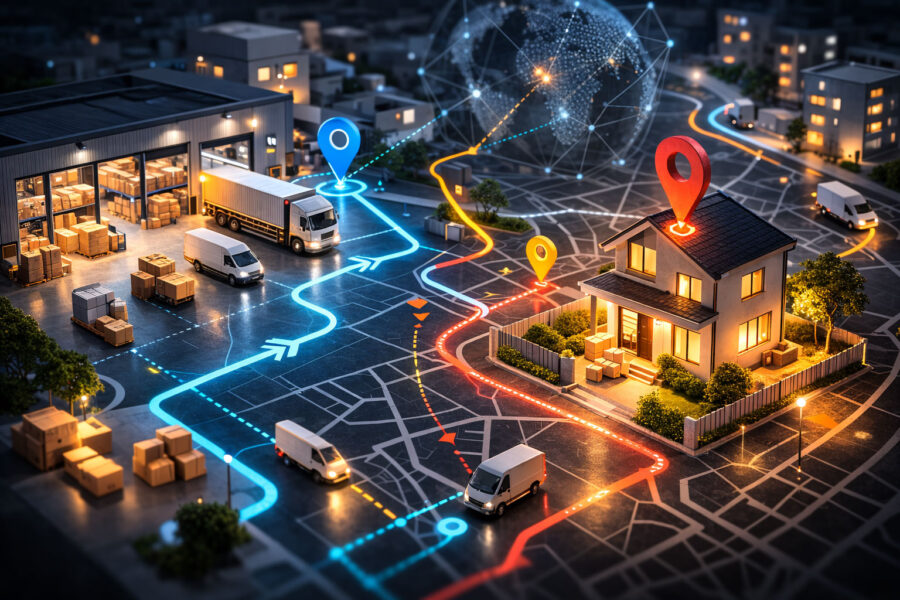
For most of modern retail history, customers believed delivery was free. Pizza arrived at the door, parcels appeared at the gate, and nobody paused to consider the economics behind that final kilometre between warehouse and doorstep. The cost existed, of course, but it remained buried inside the product price. Delivery was a service, not a product.
That illusion has now collapsed. The last mile is no longer invisible. It has become a menu of choices. Two-hour delivery, four-hour delivery, same-day delivery, next-day delivery, scheduled delivery windows, and standard shipping now exist as separate products with distinct operational costs. Customers still hesitate to pay for faster delivery, but the logistics industry increasingly treats speed itself as a priced service.
The shift reflects something deeper than marketing. It reflects the hard mathematics of logistics.
Half the Cost Lives in the Last Mile
Industry practitioners often estimate that the final delivery stage accounts for roughly half of the total door-to-door logistics cost. The exact number varies depending on geography, order density, route structure, and product characteristics, but the underlying reality remains consistent. The last mile is the most expensive part of the journey.
Several variables drive that cost. Customer density determines how efficiently vehicles can complete routes. Distance from the nearest fulfilment centre affects fuel and labour. Urban regulations restrict certain vehicle types during particular hours. Acceptance windows force drivers to revisit locations or idle while waiting. Weather, product fragility, and order value introduce further complications. Returns and collections multiply complexity again.
For low-value products, these costs make “free delivery” economically irrational. Someone always pays for it. Either the retailer absorbs the cost, the supplier raises product prices, or venture capital temporarily subsidizes the illusion of convenience.
India’s Rapid Acceleration
In India, the evolution of last-mile logistics has been particularly dramatic. Within little more than a decade, large B2C e-commerce firms have achieved delivery performance that matches or exceeds many international standards. Technology platforms, routing systems, and fulfilment networks improved rapidly, and Amazon’s investments in logistics technology remain a benchmark for the industry.
Other firms approached the problem from different directions. Some focused on connecting shippers to freight capacity. Others tried to build consumer-centric delivery experiences. Some targeted the fleet owners and drivers themselves. Others concentrated on payment reconciliation and delivery confirmation. Not every model succeeded. Some platforms failed because they solved problems customers did not truly have.
Nevertheless, the experimentation reshaped expectations across the market.
B2B Expectations Follow
The consequences now extend beyond consumer e-commerce. Retailers in industries such as pharmaceuticals, auto spare parts, construction materials, restaurants, and hospitality increasingly expect the same delivery speed and predictability. The distinction between B2C and B2B service expectations is fading.
Part of this change stems from the influx of capital into logistics technology startups. Young founders, often with advanced degrees and strong technical teams, began tackling problems that traditional logistics operators had managed through experience rather than structured optimisation. Many older distribution systems relied heavily on managerial authority and long-standing relationships rather than mathematical planning models.
Modern logistics, by contrast, requires algorithms, data visibility, and integration across systems.
The Operational Questions
Optimising last-mile logistics requires decisions across several operational dimensions.
Customer interaction. Delivery experiences are no longer passive. Customers want the ability to change delivery time windows or delivery locations. The key operational question becomes how late those changes can be accommodated without disrupting route optimisation.
Scheduling logic. Dispatching systems must continuously evaluate delivery sequences. Should deliveries follow first-in-first-out rules? Least-cost routing? Fastest completion? Some hybrid approach that accounts for service windows, vehicle capacity, and driver availability?
Load consolidation. Every delivery network attempts to maximize vehicle utilisation. Improving weight-to-volume ratios reduces unit shipping cost, but consolidation may increase delivery time or complexity.
Returns and collections. Reverse logistics is often more expensive than forward delivery. Handling product returns, cash collections, and exchange deliveries requires additional operational capacity and careful route planning.
Each of these decisions affects cost structure and service quality simultaneously.
Measuring Performance
A sustainable last-mile model also requires measurable performance metrics. Delivery success rates, cost per shipment, route efficiency, on-time arrival, and return handling costs must all be tracked consistently. These metrics form the basis for contractual relationships between logistics providers and the businesses they serve.
Without clear metrics, last-mile logistics easily becomes a negotiation driven by anecdote rather than data.
Integrating the Digital Core
Equally important is integration with enterprise systems. Last-mile delivery platforms must exchange information with ERP, order management, and warehouse systems. Businesses need visibility into delivery status, fulfilment delays, and cost-to-serve by order, product, location, and customer segment.
Capturing this information requires thoughtful integration architecture. Poor integration produces fragmented data and unreliable metrics. Strong integration creates the operational visibility needed for continuous improvement.
Choosing the Right Platform
Not every company needs the technological sophistication of Amazon. Many businesses can operate effectively using simpler routing and dispatch platforms tailored to their scale and delivery patterns. The challenge lies in selecting tools that match operational complexity without over-engineering the system.
A small regional distributor does not need a global logistics control tower. A national e-commerce network might.
Who Owns Optimisation?
The final question is the most strategic one. Who should optimise the last mile?
Logistics providers possess operational expertise and routing infrastructure. Technology companies build platforms and analytics engines. Retailers and manufacturers understand customer expectations and demand patterns. In practice, optimisation emerges from collaboration among all three.
No single actor can solve the problem alone. The economics of the last mile demand shared responsibility, shared data, and shared incentives.
The final kilometre may be short in distance. In complexity and cost, it is often the longest part of the journey.